Retirement and beyond seminar
In this session, you'll discover options to take advantage of your super before you scale back or stop working, as well as explore the financial options for retirement and continuing your lifestyle.
Book your spotTurning 65 is a significant milestone when it comes to your super. It’s the age you can freely access your super — and how you set it up now can shape what you have to live on for years to come.
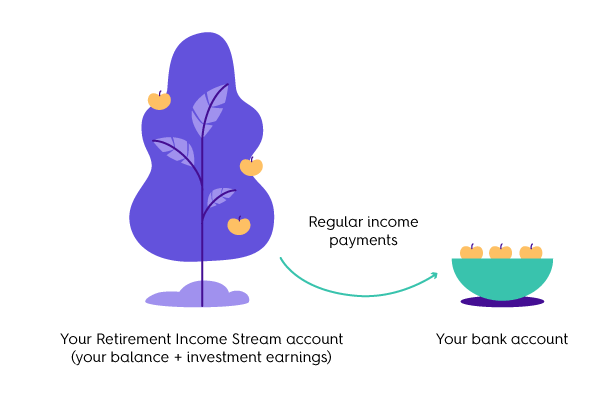
It's simpler than you might think. When you open a HESTA Income Stream, your super moves into a dedicated income stream account that stays invested and keeps earning returns, just like it does now — but can have the added bonus of tax-free payments from age 60 and tax-free investment earnings, unlike a super account.
From there, regular payments go straight into your bank account. You choose how much and how often, (government minimum limits apply).
Your balance reduces over time as payments are made, but your tax-free investment earnings can keep working to offset that.
Thinking about opening an income stream but have questions? We tackle the five questions members raise most often.
Our research shows that Australians are missing out on billions of dollars in tax-free retirement savings by not transitioning to the retirement phase – that is, opening an income stream – when eligible.
In 2024-25 alone, 83,000 HESTA members missed out on $69 million in tax benefits by staying in accumulation.*
The longer you wait, the more you leave on the table.
Read more about the benefits of making the switch.
* HESTA research conducted for HESTA by Laneway Analytics, December 2025.
Linh is 65, has $180,000 in her super, has a partner, and owns her home.
If she never transitions to an income stream, modelling suggests her retirement income could total around $505,000 over her lifetime.
If she transitions now, that figure rises to $787,000 — a difference of $282,000, or 56% more.
Why? As she draws down her super as payments, her assessable assets fall — which means her Age Pension entitlement rises. The system works in her favour, but only if she makes the move.
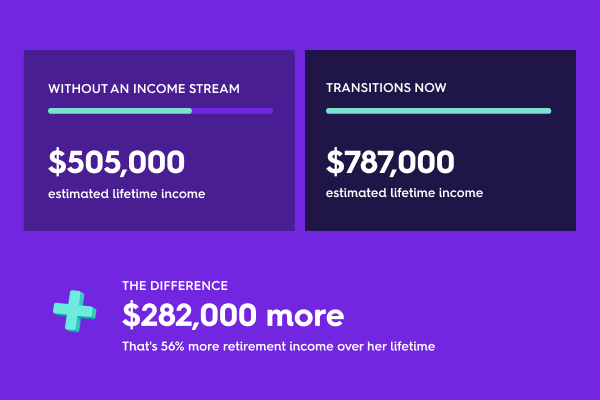
*Modelling based on 6% return in accumulation phase and 6.5% in retirement phase, calculated to age 92 consistent with ASIC's RG276 requirements. Does not account for assets outside super, lump sum withdrawals or individual life expectancy.
 Tax-free from 60
Your income payments and investment earnings are generally tax-free, unlike super in an accumulation account. Every dollar you've worked hard for stays yours.
Invest your way
Choose a ready-made strategy designed to reduce risk over time or build your own. Either way, your money keeps working for you.
You set the terms
You choose how much you receive (above government-set minimums) and how often and adjust it as your needs change. Full control, always.
Manage it anytime
You have full visibility of your account online, wherever you are.
Works with the Age Pension
When structured the right way, your income stream tops up your Age Pension if you are eligible at 67, giving you more to live on each month. It's worth talking to us about how to set it up.
HESTA Retirement Reward
When you start a HESTA Retirement Income Stream, you could be eligible for the HESTA Retirement Reward.

In this session, you'll discover options to take advantage of your super before you scale back or stop working, as well as explore the financial options for retirement and continuing your lifestyle.
Book your spot
From online calculators and videos to super advice and support from our partners — take a look at all the tools and services HESTA can offer you.
See services and tools
The HESTA App lets you access your super account from anywhere, anytime. You can use it to view your investments, update details and see how your super is tracking.
Get the HESTA AppYou don't have to figure this out alone. Our team can walk you through whether a HESTA Retirement Income Stream suits your situation - and help you get set up if it does.