salary sacrifice
Boost your super with extra contributions from your before-tax pay through salary sacrifice. A little extra now can go a long way tomorrow.
On this page:
what is salary sacrificing?
Salary sacrificing is when you arrange for your employer to put some of your take-home pay into your super account before income tax is deducted. This is in addition to the superannuation guarantee contribution your employer makes based on your qualifying earnings.
What are qualifying earnings?
Qualifying earnings (QE) are what you earn for your ordinary hours of work. This generally includes your regular pay, commissions, shift loadings, and some allowances and bonuses. It generally doesn’t include overtime payments.
Your employer works out your super guarantee contribution on your QE before any salary sacrifice is taken out, so salary sacrificing doesn’t reduce what your employer has to pay.
So, while you may ‘sacrifice’ some of your take-home pay, you may be able to benefit by boosting your retirement savings tomorrow and reducing your taxable income today.
Salary sacrifice contributions are a type of concessional (before-tax) contribution.
Before you salary sacrifice to your super, you should consider your current financial situation and how much additional money you can afford to put away, given you generally won't be able to access it until you meet a condition of release.
Grow your super
Tipping some of your before-tax salary into your super could make a real difference in the future. You can put in as little or as much as you can afford each financial year, generally up to (this includes employer contributions).
Save on tax
Before-tax salary put directly into super is generally taxed at 15%. If this is less than your marginal income tax rate, this could potentially reduce the amount of tax you have to pay.
important things to know about salary sacrificing
If you're a middle to high-income earner, you might save tax by making concessional (before-tax) super contributions. This is because the tax you pay on your super is generally less than the tax you pay on your income from salary.
However, concessional contributions may not be as tax-effective for low-income earners. If you're a low-income earner and are looking for ways to boost your super, a government co-contribution could be a good option for you.
Tax on, tax off: know your limits
Before-tax (concessional) contributions
There's a limit on the total amount of before-tax (concessional) contributions that can be made into your super account each financial year. Concessional contributions are your employer contributions (including those made as salary sacrifice) and personal contributions you claim as a tax deduction. If you go over the limit, you might pay extra tax.
The before-tax or concessional contribution cap for everyone is generally .
Your cap may be higher if your total super balance is below $500,000 on 30 June and the contributions made to your account are below the cap in previous financial years. This is known as the carry forward of unused concessional contributions cap. You can check if you have available cap capacity using the ATO services via your myGov account.
Things to consider
- If you exceed your concessional contributions cap in a financial year the excess amount is included in your assessable income and taxed at your marginal tax rate.
- You may also pay extra tax as the government applies a 15% tax offset (representing the amount of tax you’ve already paid when it was contributed to your super account). You may be able to elect to withdraw up to 85% of your excess concessional contributions to help pay the tax liability.
- Any excess concessional contributions that are not taken from your super balance count toward your non-concessional contributions cap.
Tax for high income earners
If your income and before-tax (concessional) contributions during the financial year total more than you could pay an additional 15% tax (up to 30% in total) on some or all the contributions made to your super in the financial year. If you have to pay the extra tax, you’ll receive a notice of assessment from the ATO. You can pay the extra tax directly or allow the ATO to release it from your super fund.
For more information on the ways you can add to super, contribution caps and much more, read How super is taxed (PDF).
see the difference it could make
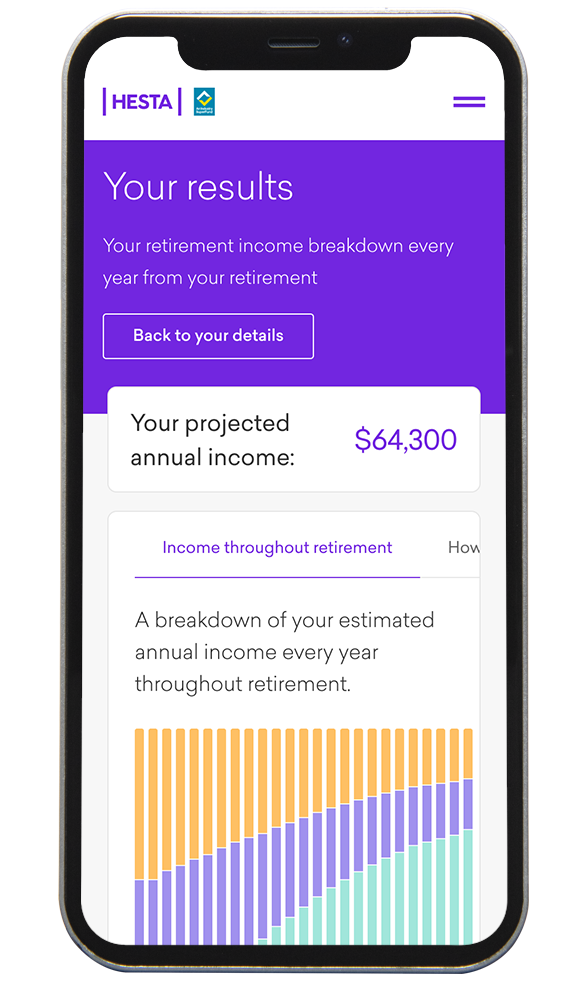
Our Future Planner tool may help take away the mystery around your financial future.
See how much money you’re projected to have in retirement and your options for growing your super – including how regular contributions via salary sacrifice can impact your super savings. Log in and go to the ‘Advice and help’ section to get started.
Log in to explore Future Planner
set up salary sacrifice
Decide how much you want to put into your super from each pay, then follow these steps:

Complete the form
Complete the Salary sacrifice form (PDF) and provide it to your employer/payroll department.

Check your payslip
Once it has been set up, your next payslip should show the amount you're adding to your super.
what to do if you're self-employed or your employer doesn't offer salary sacrifice
An alternative could be to make after-tax (non-concessional) contributions to your super directly and claim the deduction on your tax return. If you do claim a tax deduction, this will change the amount claimed to a before-tax (concessional) contribution. This is an option if your employer doesn't offer salary sacrifice or if you are fully (or mostly) self-employed.
More on after-tax contributions
Need some expert help with contributions?
Chat with our advice team over the phone at no extra cost: it’s all part of being with HESTA.